Yes. The State Pension is a UK social security benefit, but it is also an entitlement for people who satisfy the relevant State Pension rules.
Unlike means-tested support, the amount someone receives is primarily connected to their National Insurance record and when they reach State Pension age, rather than how much money they have in savings.
That distinction matters in 2026. The full new State Pension is now £241.30 a week, while the State Pension age is moving gradually from 66 to 67 between 2026 and 2028.
Someone may therefore have built a substantial future pension entitlement but still be unable to receive it until reaching their individual State Pension age.
Being described as a benefit also does not mean that the State Pension works in the same way as Universal Credit or Pension Credit. Each has different eligibility, income and savings rules.
Is the State Pension Officially Classed as a Benefit in UK Law?
There is unusually clear legal evidence for the answer. Section 1 of the Pensions Act 2014, which created the new State Pension framework, states that Part 1 of the Act creates “a benefit called state pension”.
This is more significant than simply describing the State Pension informally as government support. The legislation itself uses the term benefit.
At the same time, the Act refers to whether a person is entitled to that benefit. The two descriptions therefore do not contradict each other. The State Pension can legally be a benefit while an individual has an entitlement to receive it after satisfying the applicable conditions.
What Does “Benefit” Mean in This Context?
The word benefit is broader in social security law than it is sometimes used in everyday conversation.
Calling the State Pension a benefit does not mean:
- It Is Automatically Means-Tested: State Pension qualification is primarily linked to age and National Insurance history.
- Only People On Low Incomes Can Receive It: Income and savings do not normally determine whether someone receives their State Pension.
- It Is A Discretionary Payment: People who satisfy the relevant conditions have an entitlement under the pension rules.
- National Insurance Creates A Personal Pension Account: NI contributions help establish entitlement, but they do not create an individual investment pot in the claimant’s name.
This is why someone can accurately describe the State Pension as both a benefit and an earned entitlement.
Why Is the State Pension Also Described as an Entitlement?
An entitlement is a person’s right to receive something after meeting specified conditions.
For the new State Pension, the important conditions normally include reaching State Pension age and having enough qualifying years on the person’s National Insurance record. The amount then depends on that record and, for people with pre-April 2016 history, transitional rules may also apply.
For example, someone aged 65 could already have 35 or more qualifying years. That does not mean their State Pension becomes payable immediately. They still have to reach their individual State Pension age.
The distinction can therefore be summarised simply:
| Term | What It Means |
| Benefit | The type of government social security payment |
| Entitlement | The individual’s right to receive that payment after satisfying its rules |
| State Pension Amount | The amount calculated under the applicable pension and NI rules |
It is therefore misleading to argue that the State Pension cannot be a benefit simply because someone spent decades paying National Insurance.
How Does Your National Insurance Record Affect State Pension Entitlement?
The new State Pension is mainly based on a person’s National Insurance record.
A qualifying year can be created in several ways, including:
- Paying National Insurance Contributions Through Work
- Receiving Certain National Insurance Credits
- Paying Eligible Voluntary National Insurance Contributions
Under the new State Pension rules, a person normally needs at least 10 qualifying years to receive any new State Pension. These years do not necessarily have to be consecutive.
People whose National Insurance record started after April 2016 generally need 35 qualifying years to receive the full new State Pension. The calculation can be more complicated for people whose record began before the new system was introduced.
Do 35 Qualifying Years Always Mean You Get the Full State Pension?
No. The frequently quoted 35-year rule does not guarantee the full new State Pension for everyone.
People who had National Insurance history before 6 April 2016 can fall under transitional calculations. Previous periods of contracting out of the Additional State Pension may also affect how much State Pension the person has built.
GOV.UK states that someone who was contracted out will usually need more than 35 qualifying years to receive the full new State Pension.
This is one reason individual forecasts matter more than simply counting qualifying years. Questions around contracting-out records have also contributed to cases involving incorrect State Pension forecasts, particularly for people with older workplace pension histories.
How Much Is the State Pension in 2026/27?
State Pension rates increased again from April 2026.
| State Pension Type | 2025/26 Weekly Rate | 2026/27 Weekly Rate |
| Full New State Pension | £230.25 | £241.30 |
| Full Basic State Pension, Category A or B | £176.45 | £184.90 |
The full new State Pension therefore increased by £11.05 a week, while the full basic State Pension increased by £8.45 a week.
The increase forms part of the wider State Pension triple lock, which protects the basic and new State Pension through annual uprating based on earnings, inflation or the 2.5% minimum.
However, the headline £241.30 figure is not what every pensioner receives. An individual’s payment can be lower, or in some transitional cases higher, depending on their National Insurance and pension history.
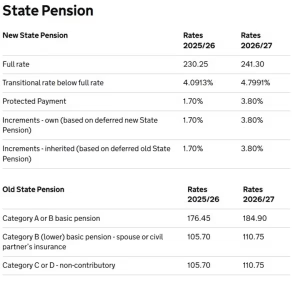
UK State Pension weekly rates for 2026/27, including the full new State Pension and basic State Pension.
Is the State Pension Means-Tested?
The State Pension is not generally means-tested.
New State Pension eligibility is based principally on reaching State Pension age and having the required National Insurance record. The standard eligibility rules do not impose the type of income and savings assessment used for means-tested support such as Pension Credit.
This means a person can still qualify for State Pension even if they have:
- Substantial Savings
- A Workplace Pension
- A Private Pension
- Investment Income
- Employment Earnings After State Pension Age
Their personal financial circumstances may affect tax or entitlement to other benefits, but they do not normally erase State Pension entitlement already established under the applicable rules.
Can Savings or Earnings Reduce Your State Pension?
Savings do not normally reduce the State Pension itself.
This is very different from Pension Credit, where financial circumstances are assessed. For Pension Credit in 2026/27, the first £10,000 of savings and investments does not affect the calculation. Above £10,000, every £500 or part of £500 is treated as £1 of weekly income.
People can also continue working after reaching State Pension age and still claim their State Pension. GOV.UK confirms that there is no general requirement to stop working at State Pension age.
Earnings can, however, increase total taxable income.
How Is the State Pension Different From Pension Credit and Universal Credit?
All three sit within the broader social security system, but they perform very different roles.
| Payment | Main Basis | Means-Tested? | Typical Position |
| State Pension | State Pension age and NI record | No Standard Means Test | Retirement-age income |
| Pension Credit | Income and personal circumstances | Yes | Additional support after qualifying age |
| Universal Credit | Income, earnings and circumstances | Yes | Primarily working-age support |
Pension Credit is explicitly separate from the State Pension. It is designed to provide additional financial support to eligible people over State Pension age who have lower incomes.
Universal Credit generally applies before State Pension age, although particular rules can apply to mixed-age couples and certain people who moved to Universal Credit through the managed migration process.
The important point is that describing all of these payments as benefits does not mean they have identical qualification rules.
How Much Does the Government Spend on State Pension Benefits?
Government expenditure data provides further evidence of how the State Pension is treated within the benefit system.
Department for Work and Pensions statistics show that State Pension expenditure increased from £136.4 billion in the financial year ending 2025 to £146.1 billion in the financial year ending 2026.
More importantly for the question of classification, the DWP describes State Pension as the benefit with the highest expenditure, accounting for almost half of total benefit expenditure.
That does not determine an individual’s entitlement, but it clearly demonstrates that official government statistics classify State Pension spending within the wider benefits system.
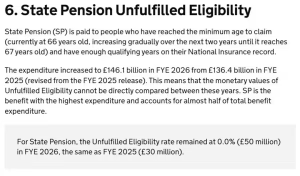
DWP figures showing State Pension expenditure reaching £146.1 billion in the financial year ending 2026.
Why Does the State Pension Age Change Matter in 2026?
The State Pension age transition from 66 to 67 is now underway.
Under the legislated timetable, the increase takes place gradually between 2026 and 2028.
People born between 6 April 1960 and 5 March 1961 reach State Pension age at different points between 66 years and one month and 66 years and 11 months. Those born from 6 March 1961 through the relevant later birth-date range reach State Pension age at 67 under the current timetable.
State Pension Age During The 2026–28 Transition
| Date Of Birth | State Pension Age |
| 6 April 1960 To 5 May 1960 | 66 Years And 1 Month |
| 6 June 1960 To 5 July 1960 | 66 Years And 3 Months |
| 6 September 1960 To 5 October 1960 | 66 Years And 6 Months |
| 6 December 1960 To 5 January 1961 | 66 Years And 9 Months |
| 6 February 1961 To 5 March 1961 | 66 Years And 11 Months |
| From 6 March 1961 Within The Current 67-Age Range | 67 |
The exact date matters because a strong National Insurance record does not allow someone to claim early. GOV.UK states that the earliest a person can normally receive their State Pension is when they reach their State Pension age.
Does Reaching State Pension Age Mean Payments Start Automatically?
No. The new State Pension is not automatically paid simply because someone reaches State Pension age.
A person normally needs to claim it. GOV.UK says people approaching State Pension age can claim online, by phone or, where applicable, through other claim routes.
This creates another useful distinction between entitlement and payment. Someone may satisfy the age and contribution conditions but still need to complete the claiming process before receiving regular payments.
Can You Defer the State Pension?
Yes.
If someone does not claim their State Pension when they reach State Pension age, it normally defers automatically. They do not need to make a separate application simply to start the deferral period.
Deferring can potentially increase later State Pension payments, although the outcome depends on when the person reached State Pension age and their circumstances. Certain benefits can also affect the ability to build up extra State Pension through deferral.
Deferral should therefore be considered in the context of overall retirement income rather than automatically assumed to be financially beneficial.
Is the State Pension Taxable Even Though It Is a Benefit?
Yes. The State Pension is taxable income.
Tax is not normally deducted directly before the State Pension reaches the recipient. Instead, HMRC considers the person’s State Pension together with other taxable income. Tax becomes due where total taxable income exceeds the allowances available to that individual.
Other taxable income can include:
- Employment Earnings
- Workplace Or Private Pension Income
- Additional State Pension
- Certain Savings Or Investment Income
- Other Taxable Benefits
This is another example of why the word “benefit” should not be confused with “tax-free”.
The issue has become increasingly visible as State Pension payments rise, including through cases such as Alan Perkins’ State Pension tax position, where State Pension and additional retirement income illustrate how a pensioner’s total taxable income can move above the tax-free allowance.
State Pension Vs Workplace And Private Pensions
The State Pension should not be confused with a personal retirement fund.
National Insurance contributions help establish entitlement under State Pension rules, but there is no individual State Pension investment pot containing a person’s NI contributions.
A workplace or personal pension usually works differently. Contributions are paid into a pension arrangement for the individual and may be invested to provide retirement income.
| Feature | State Pension | Workplace Or Personal Pension |
| Main Basis | NI record and State Pension rules | Pension contributions and scheme rules |
| Personal Investment Pot | No | Usually Yes For Defined Contribution Schemes |
| Minimum State Pension Age Applies | Yes | State Pension age does not determine normal access |
| Amount Determined By | Government pension rules and NI history | Scheme type, contributions, investment performance or promised benefits |
Defined benefit workplace schemes are different again because they normally promise retirement income under the scheme formula rather than simply paying out an investment pot.
For many people, the State Pension therefore forms only one part of total retirement income. GOV.UK similarly describes it as a foundation alongside workplace pensions, other pensions and earnings.
What Should You Check Before Relying On Your State Pension?
General rules cannot tell someone exactly what they will receive. Personal pension outcomes can differ because of National Insurance history, contracting out, credits and transitional arrangements.
Before making retirement decisions, it is sensible to:
- Check Your Exact State Pension Age
- Obtain An Up-To-Date State Pension Forecast
- Review Your National Insurance Record
- Look For Missing Or Incomplete Qualifying Years
- Check Whether NI Credits Should Have Been Added
- Identify Any Previous Contracted-Out Pension History
- Check Whether Voluntary Contributions Would Actually Increase Your Pension
- Consider Pension Credit Separately If Your Retirement Income Is Low
A State Pension forecast is particularly important because the headline full rate does not tell an individual what they will personally receive.
Someone thinking of paying voluntary National Insurance should also establish whether buying an extra qualifying year would genuinely increase their pension. Transitional calculations can mean an extra contribution does not produce the same result for everyone.
Conclusion
The State Pension is both a benefit and an entitlement. UK legislation expressly describes it as a benefit, while an individual’s entitlement depends on meeting the relevant State Pension age and National Insurance conditions.
What makes the State Pension different from many payments commonly associated with the benefits system is that it is not generally means-tested. Savings or higher income do not normally remove an established State Pension entitlement, although they can affect tax and eligibility for separate means-tested support.
With the full new State Pension at £241.30 a week in 2026/27 and the State Pension age moving gradually towards 67, people approaching retirement should focus on their own State Pension age, NI record and forecast rather than relying only on the headline pension rate.
FAQs
Is the State Pension Legally a Benefit?
Yes. Section 1 of the Pensions Act 2014 explicitly creates a “benefit called state pension”. A person can therefore be legally entitled to a benefit without that benefit being means-tested.
Does Receiving State Pension Mean You Are “On Benefits”?
In the formal social security sense, the State Pension is a benefit. In everyday conversation, however, the phrase “on benefits” is often used more narrowly for means-tested or working-age support, which can cause confusion.
Is State Pension An Earned Entitlement?
It can reasonably be described as an entitlement because a person’s right to receive it depends on satisfying State Pension rules. For the new State Pension, National Insurance contributions and credits are central to building qualifying years.
Is State Pension Means-Tested?
No standard income or savings means test applies to the State Pension. Eligibility is primarily determined by State Pension age and the person’s National Insurance record.
Can Millionaires Receive The State Pension?
Yes, provided they satisfy the applicable State Pension eligibility rules. Wealth alone does not remove a State Pension entitlement because it is not generally means-tested.
Does State Pension Count As Taxable Income?
Yes. State Pension is taxable income, although whether any Income Tax is actually due depends on the person’s total taxable income and available allowances.
Can You Receive State Pension While Still Working?
Yes. A person can normally continue working after State Pension age while receiving their State Pension. Reaching State Pension age does not generally require someone to retire from employment.